Blog > How Do I Check If a House in Acadiana Is in a Flood Zone Before I Fall in Love With It?
How Do I Check If a House in Acadiana Is in a Flood Zone Before I Fall in Love With It?
by
How Do I Check If a House in Acadiana Is in a Flood Zone Before I Fall in Love With It?
Last Updated: September 11, 2026
Quick answer: Check FEMA's Flood Map Service Center by address before your first showing, then confirm with a licensed flood insurance agent — FEMA's zone tells you the regulatory category, but not your actual premium or real-world risk. In Acadiana, plenty of homes outside "high-risk" zones still flooded in August 2016, so a Zone X label isn't a guarantee of zero risk.
What do the different flood zone letters actually mean?
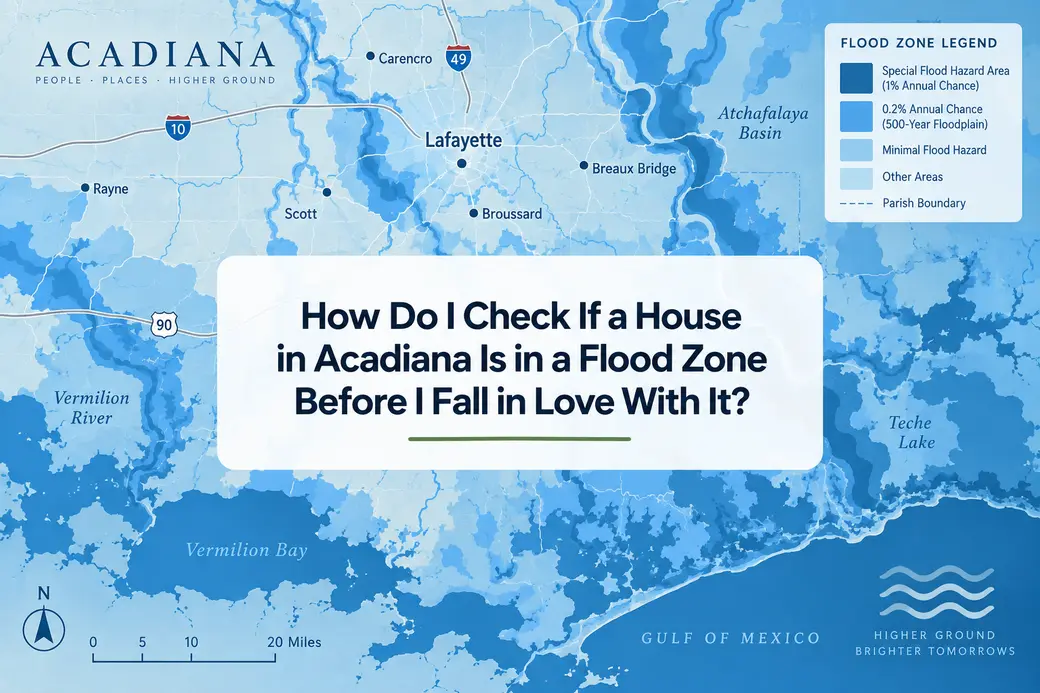
FEMA flood zones aren't a simple "safe vs. unsafe" system — they're statistical risk categories:
| Zone | What It Means |
|---|---|
| Zone AE / A | High-risk ("Special Flood Hazard Area"); 1% annual chance of flooding. Flood insurance is required if financed. |
| Zone X (shaded) | Moderate risk; 0.2% annual chance of flooding. Insurance optional but often advisable. |
| Zone X (unshaded) | Minimal risk relative to mapped floodplains. Insurance optional and often inexpensive. |
| Zone AO/AH | Shallow flooding risk from sheet flow or ponding, common in flat low-lying areas. |
The key nuance for Acadiana buyers: these maps are based on historical modeling, not a guarantee of what will happen in the next storm. Zone designation changes over time too, as FEMA updates flood studies.
How do I actually look up a specific address?
- Start with FEMA's Flood Map Service Center (msc.fema.gov) — enter the property address to see its official flood zone designation and view the FIRM (Flood Insurance Rate Map) panel.
- Cross-check with the parish's GIS mapping tool, which often layers in more granular local drainage and elevation data than the national FEMA viewer.
- Ask for the property's elevation certificate, if one exists — this document shows the home's actual elevation relative to the "base flood elevation" and is far more predictive of real risk than the zone label alone.
- Get a flood insurance quote directly, since insurers price based on distance to water, elevation, and building characteristics under FEMA's Risk Rating 2.0 system — not just the zone box.
Why isn't "not in a flood zone" the same as "won't flood"?
This is the single most important thing I tell out-of-town buyers moving into Acadiana. During the August 2016 flood, a large share of the homes that took on water were outside FEMA's mapped high-risk zones entirely — because the event exceeded what the historical models predicted, and because drainage and rainfall-driven flooding doesn't always follow river or coastal flood modeling. A "Zone X" label reduces your statistical risk and your insurance requirement; it does not eliminate the value of carrying a policy.
What should I actually do with this information as a buyer?
Don't let a flood zone designation alone make or break a home for you — use it as one input alongside elevation, drainage history, and a real insurance quote. I've had clients walk away from beautiful homes in Zone X because a quick insurance quote came back cheap and reassuring, and I've had clients proceed confidently on Zone AE homes because the elevation certificate showed the structure sitting well above the base flood elevation, keeping the premium manageable. The zone letter is a starting point for the conversation, not the whole conversation.
My take, as a local agent
I pull the flood zone for every listing before I ever schedule a showing with a client — not after they've fallen for the kitchen. It saves heartbreak and it saves negotiating leverage, because if a flood disclosure or elevation issue comes up mid-contract, you've lost your strongest negotiating position. Acadiana's flat terrain and drainage patterns mean flood risk is genuinely hyper-local — sometimes block by block — so I always encourage a real quote over an assumption based on the zone label alone.
Frequently Asked Questions
Is flood insurance required if my home is in Zone X? Generally no — lenders typically only require it for homes in FEMA high-risk zones (like AE or A). Coverage in Zone X is optional but often inexpensive and worth considering given Acadiana's flooding history.
How accurate are FEMA flood maps? They're based on historical data and modeling, updated periodically, but they don't account for every real-world scenario — extreme rainfall events like August 2016 flooded many homes outside the mapped high-risk areas.
What is an elevation certificate and do I need one? It's a document showing a structure's elevation relative to the base flood elevation for its zone. It's not always required, but it can significantly affect your insurance premium and is worth requesting during due diligence.
Can a home's flood zone change after I buy it? Yes. FEMA periodically updates flood maps based on new studies, development changes, and drainage infrastructure, which can move a property into a different zone over time.
Alyson is a Realtor® serving buyers and sellers across Acadiana. Flood zone information should always be verified directly through FEMA's Flood Map Service Center and a licensed insurance professional for the specific property in question.
Alyson Finch, REALTOR®
Living in the 337 • Real Broker, LLC
337.280.9651
alyson@livinginthe337.com
LivingInThe337.com
Let's get you living in the 337!
GET MORE INFORMATION